 The Geek Circle The Voice of Africa’s Tech Community
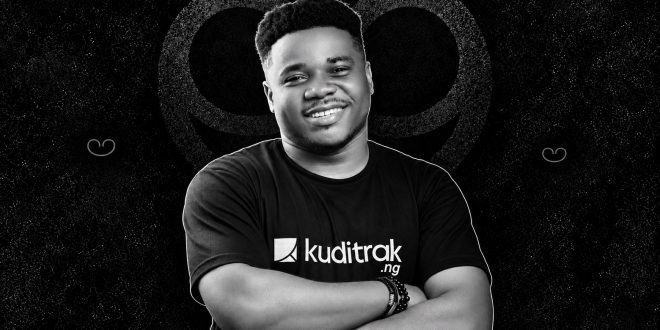
After years of building software for clients, Confidence Emonena is tackling a problem he knows personally: earning money, spending it across several accounts, and struggling to explain what is left.
There was a period when Dev Clinton was making good money and still finding his bank balance difficult to explain.
He would get paid with a plan for what the money should cover. Then someone needed help. A bill came up. There was transport to pay for, data to buy, money to move between accounts. Each transaction made sense at the time. Taken together, they left him wondering what had happened.
Saving did not automatically fix it. He remembers locking money away, then borrowing again before the month ended. When the savings became available, there were debts waiting for them.
That experience became the starting point for Kuditrak, the financial management company he is building from Lagos. Its founder, Confidence Emonena, is better known as Dev Clinton, a name that reflects the work he had been doing long before he had a company of his own.
In a conversation with The Geek Circle on September 20, he kept returning to the distinction behind the product.
“Moving money and understanding money are two different things.”
For Clinton, the second was the problem he had not solved.
Before Kuditrak there was a church website
Clinton traces his start in development to his church’s media department. He had been doing graphic design when he decided the church needed a website. Around 2018 or 2019, he built one and presented it to the board.
He is modest about that first attempt. It was a basic HTML and CSS site, far from the work he would later charge clients to deliver. But people could find church activities and account details for offerings. The board liked it. Something he had made was useful to people he knew.
He moved further into web development, then mobile applications and backend work. At home, however, hours spent on a laptop required explanation. His parents wanted to know what he was doing and why it was not yet bringing in money. He recalls having to reassure them that the work was legitimate. His first job helped settle the question.
By the time Kuditrak took shape, he had spent years building across sectors, including agriculture, education, healthcare and finance. One assignment stayed with him in particular.
Working on a product for One Acre Fund meant thinking about farmers who could not count on a reliable internet connection. Information needed to be captured and verified, then uploaded when connectivity returned. Clinton travelled from Lagos through Abuja to Minna to demonstrate the product and see the conditions for himself.
It changed what he paid attention to. A feature could work on his own phone and still fail the person who needed it. That lesson would follow him into a product where an incorrect transaction record could quickly cost a user’s trust.
A personal problem becomes a company
The idea for Kuditrak dates to 2022. The first version was straightforward: bring several bank accounts into one place, show balances and transactions, and help him budget around them.
Clinton had four or five accounts at the time. Keeping track meant piecing together activity scattered across different apps. He wanted to open one application and understand what was happening.
When he showed the product to Oluwafemi Ayemimowa, a designer who would become his co-founder, the response went beyond improving how it looked. Oluwafemi recognised the problem from his own life. He contributed product ideas as well as design work, giving Clinton an early indication that the frustration extended beyond his own accounts.
The company has since grown beyond that first budgeting tool. Clinton describes live features covering income and expense tracking, bank connections, financial insights, savings and wallet services. At the time of the interview, he said stable versions were available on iOS and Android, with the team preparing for wider adoption. Within three months, Kuditrak had reached 270+ users and processed over ₦34 million in transactions.
But his explanation of the product remains rooted in that original experience. A dashboard should help someone decide what to do next. Seeing where the money went is useful only if it becomes easier to make a different choice.
Making room for the way people actually earn
Clinton’s own freelance work has shaped his view of budgeting. A freelancer might receive several payments in one week and nothing for the next two. A small business owner might take in money every day. A salaried worker may know the date and amount of the next payment.
He wants Kuditrak to accommodate those differences. A predictable monthly salary cannot be the assumption behind every user’s financial life.
The same practical approach appears in his description of the app’s AI features. They are intended to work with a user’s financial information, but transaction descriptions do not always explain what a payment was for. A transfer to a person’s name could mean any number of things. Users can correct categories manually when the software gets them wrong.
Some of the most useful product lessons have come from watching what people do. Clinton recalls an early user repeatedly saving small amounts, including ₦100 and ₦200. The pattern caught his attention because savings had not been his main focus at the beginning. Someone was using the product to put money aside in increments that suited their day.
He could see the transactions; he could not know the user’s whole financial story. Still, the behaviour made him reconsider how much attention savings deserved within Kuditrak.
Group savings draw on another familiar practice. Clinton describes private groups formed by people who already know one another, with the app organising records and contributions. He deliberately avoided making groups publicly discoverable to strangers. The relationships between members still matter, even when software takes over some of the administration.
Earning trust while the company is young
Clinton is careful when asked what he can promise someone using a new financial product.
“I would never tell somebody that your money is magically risk-free because it’s inside my own application.”
Instead, he talks about accurate records, responsive support and being clear about what the product currently does. He says Kuditrak works with financial infrastructure partners, and that securing a partner licensed by the Central Bank of Nigeria helped the company move forward. The interview did not identify that partner.
There are also features he says the team has built but has not released. USD virtual cards were one example at the time of the conversation: development and testing had taken place, but the necessary arrangements were still being worked through.
The distinction matters for a young company with an expanding product. Building a feature and making it available to customers involve different responsibilities.
Those responsibilities also cost money. Clinton says Kuditrak’s free tier allows a user to connect one bank account, while paid plans support multiple connections and help cover third-party services, infrastructure and support. The challenge is to offer enough value for someone to start while paying for the systems that keep the service running.
Paying for his own decision
At the time of the interview, Clinton said Kuditrak was funded largely from his own earnings, with no investor on board yet.
Every hour spent on the company was an hour he could have billed to a client. He knew the trade-off. Eventually, he wanted to put his experience into something he would continue owning and developing, rather than completing another handover.
He does not dismiss the work that paid for that choice.
“Client work is not something you should be ashamed of doing,” he says.
It gave him experience with real customers, exposed him to unfamiliar problems and provided money to keep building. Kuditrak’s beginnings are tied to those years of work, including the less visible stretches of study, failed ideas and technical problems.
He still writes code and investigates bugs. Other days involve conversations with prospective investors or reviewing how people are using the product. Oluwafemi remains someone he turns to, and Clinton says he also works with people supporting security, legal matters and transaction monitoring. His wife is another source of support when the work becomes difficult.
He is clear that family comes first, even if the working day itself is hard to predict. Something breaks, a conversation opens up, a user reveals a problem he had not considered. The schedule changes.
What he wants Kuditrak to become
Clinton expects Kuditrak to grow beyond budgeting, but he is already having to decide which opportunities fit.
He recounts a conversation with a prospective investor who suggested adding cryptocurrency, stablecoins and ways to fund betting wallets. Clinton says he declined the direction. He could see how those features might bring in money, but they did not fit what he wanted to help users do.
His longer-term ambition is for people to manage more of their financial lives through Kuditrak. For now, his description of a successful first week is considerably smaller.
“I don’t expect their financial life to just transform immediately after seven days.”
He wants someone to open the app and understand something they could not explain before. Where is the money going? Which expense keeps returning? Are they putting anything aside towards the goal they said mattered?
Those are questions Clinton was asking before there was a company to build. They remain the questions he wants Kuditrak to answer.